XAU/USD DAILY OUTLOOK: NFP + CHINA GOLDEN WEEK COULD CREATE AN UNUSUAL VOLATILITY WINDOW
By Yaipubi Chanu | YAI
XAU/USD is trading around $4,135, below the 21-day, 50-day and 100-day SMAs concentrated around $4,290–$4,330, while the 200-day SMA remains much higher near $4,539. On the technical structure you supplied, that keeps the daily bias under pressure. RSI near 36 indicates weak momentum, although Gold is not yet deeply oversold.
The macro environment is equally important. Gold fell as low as roughly $4,111 on September 28, while US Treasury yields reached multi-year highs. Markets have been increasing expectations for another Fed hike, the Dollar has strengthened, and Chinese gold demand has softened ahead of Golden Week. Reuters
Why This NFP Could Be Different
The September US Employment Situation is officially scheduled for Friday, October 2 at 8:30 a.m. ET. The current Reuters economist consensus is approximately +100,000 payrolls with unemployment at 4.2%. Bureau of Labor Statistics
At the same time, China enters its National Day Golden Week from October 1–7. The Shanghai Gold Exchange confirms it will be closed throughout that period, with no night session on September 30 and normal trading resuming October 8. Shanghai Gold Exchange
That matters because one of the world’s largest physical Gold markets will be absent when NFP arrives.
I would describe this as reduced Chinese-market participation, rather than assuming total global XAU/USD volume must necessarily be low. London and New York liquidity will still operate normally. However, the absence of Shanghai trading and Chinese participation can remove an important source of Asian-session price discovery and physical-market arbitrage.
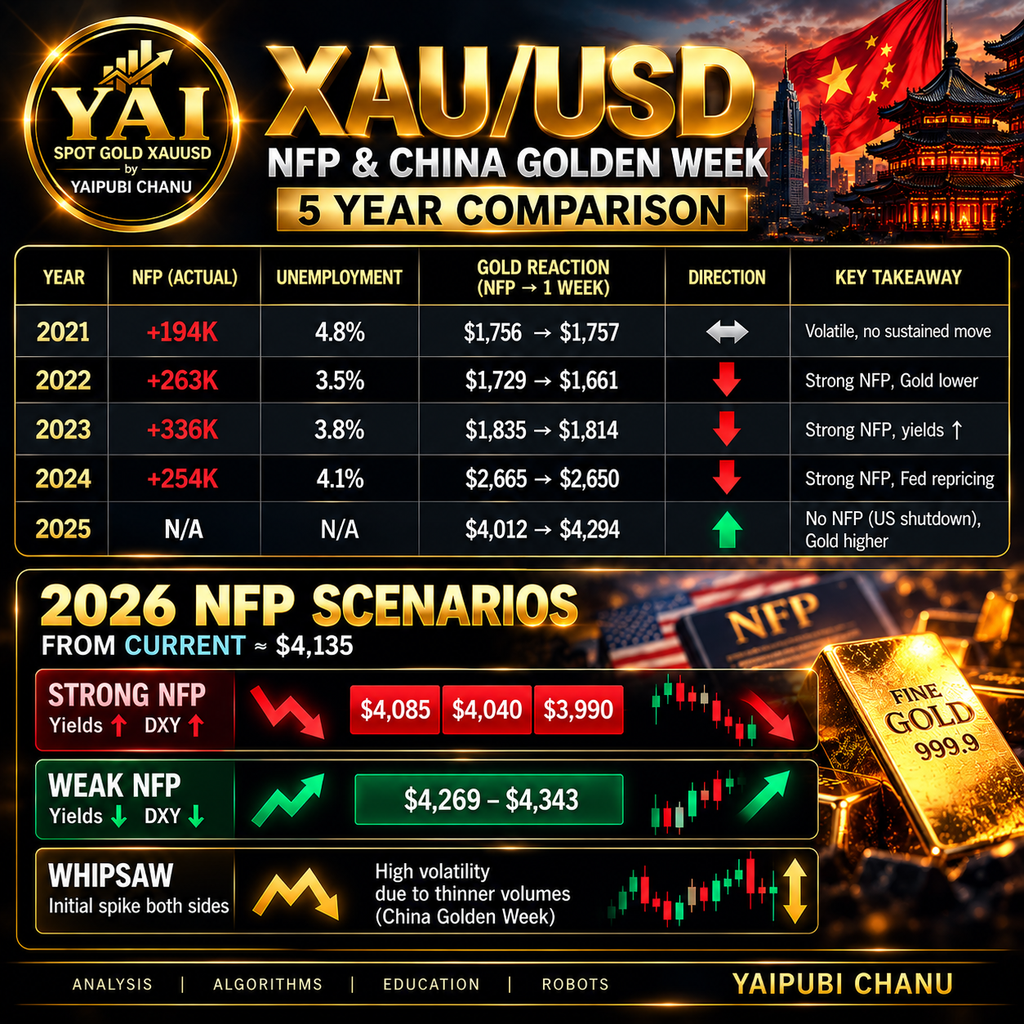
XAU/USD — Golden Week & NFP: 5-Year Comparison
| Year | Early-Oct NFP | Labour signal | Gold / macro reaction | Key takeaway |
|---|---|---|---|---|
| 2021 | +194K | Weaker payroll growth; unemployment fell to 4.8% Bureau of Labor Statistics | Gold experienced an intraday rebound but finished around $1,757, roughly flat/slightly lower; US yields rose. S&P Global | Weak headline NFP did not create a sustained Gold breakout. |
| 2022 | +263K | Solid jobs; unemployment fell to 3.5% Bureau of Labor Statistics | The report reinforced expectations for aggressive Fed tightening; Gold came under renewed pressure after its early-week recovery. | Strong labour + hawkish Fed expectations = Gold pressure. |
| 2023 | +336K | Exceptionally strong payroll growth; unemployment 3.8% Bureau of Labor Statistics | Initial reaction favored higher yields/USD and pressured Gold, although subsequent price action demonstrated the risk of reversal after the first move. | NFP can create a liquidity shock followed by reversal. |
| 2024 | +254K | Strong jobs; unemployment 4.1% Bureau of Labor Statistics | Markets sharply reduced expectations for another 50bp Fed cut; yields rose and Gold initially weakened. Reuters | Strong NFP → Fed repricing → yields ↑ → Gold pressure. |
| 2025 | No scheduled NFP release occurred | Government shutdown delayed the employment report. World Gold Council | Gold rose strongly during the period while Treasury yields softened; other labour indicators such as ADP became more important. World Gold Council | Shows that NFP itself is not necessary for major Golden Week volatility. |
What I Take From the 5-Year Pattern
The historical sample does not show a dependable rule that China’s Golden Week makes Gold bullish or bearish. Instead, the recurring driver is the change in US monetary-policy expectations after labour-market information.
My economic transmission map is:
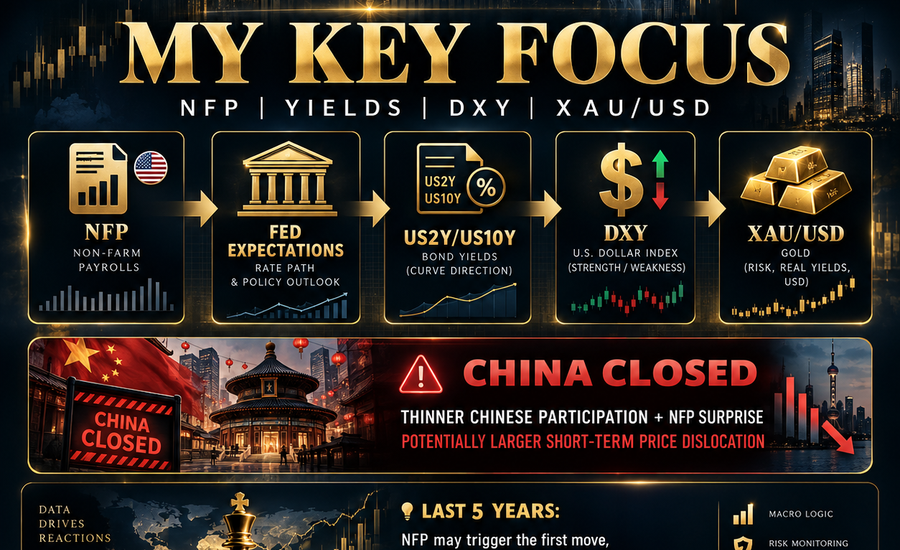
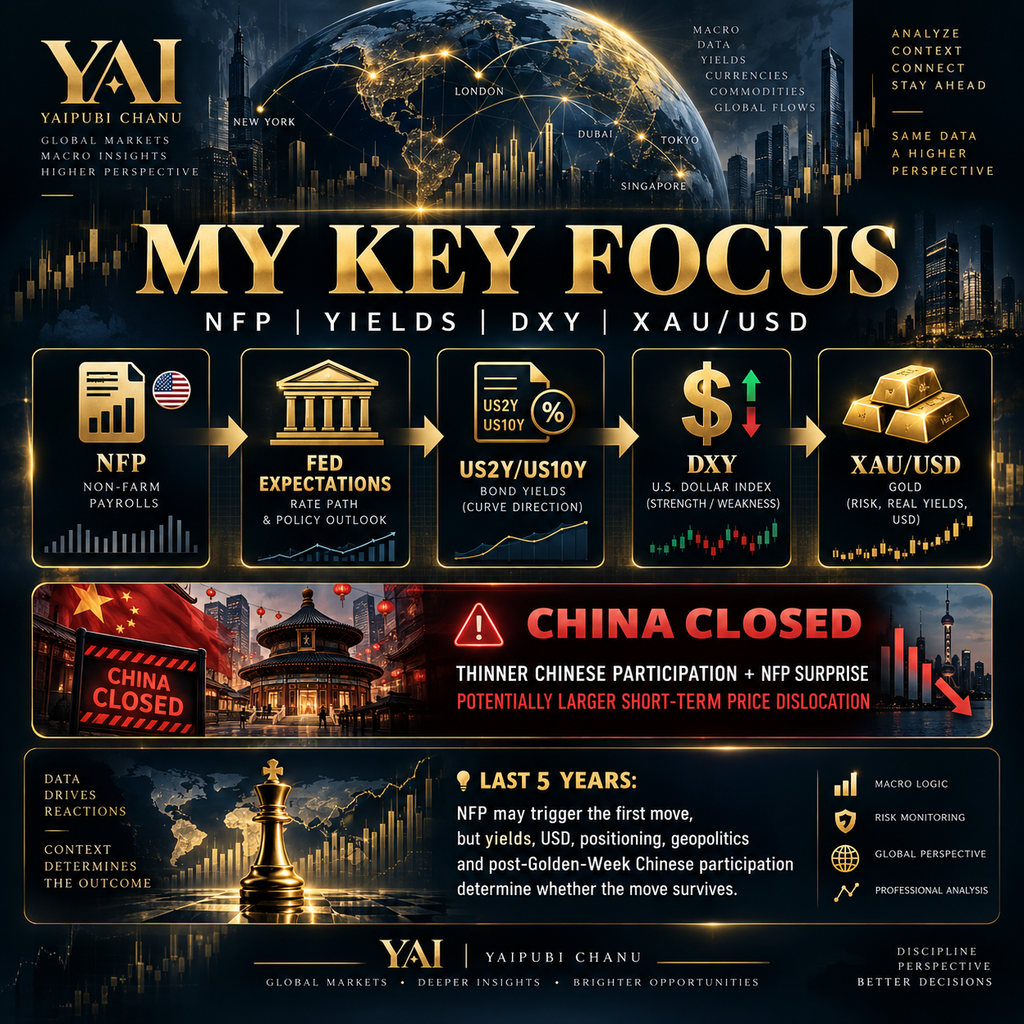
NFP → Fed Expectations → Treasury Yields → DXY → XAU/USD
China’s Golden Week can be an amplifier rather than the directional catalyst. Reduced Chinese-market participation can alter Asian liquidity and price discovery, while London and New York remain active. When China returns, physical demand, Shanghai premiums and restocking can become relevant again. The World Gold Council notes that Golden Week traditionally begins China’s peak gold-buying season, although elevated prices and weak consumer confidence have weighed on jewellery demand in 2026. World Gold Council
YAI 2026 Scenario Map
With XAU/USD around the $4,135 region, I would frame the coming NFP as scenarios rather than make a single-point prediction.
Strong NFP / wages + → Fed hike expectations ↑ → US yields ↑ → DXY ↑ → Gold ↓
$4,085 → $4,040 → $3,990/$3,969 → $3,939
Weak NFP → Fed hike expectations ↓ → yields ↓ → DXY ↓ → Gold retracement ↑
First major recovery test: $4,290–$4,330
The third possibility is particularly important during reduced Chinese participation:
NFP spike → liquidity sweep → DXY/yields reverse → XAU/USD reverses sharply.
So I would treat the first NFP move cautiously. The five-year comparison suggests that the more useful confirmation comes from what US yields and DXY do after the employment number, rather than from NFP alone.
What the Last Five Years Tell Me
The historical evidence does not support a simple rule that “Golden Week + NFP = Gold rises” or “Gold falls.” The stronger recurring relationship is that NFP changes Fed expectations, Treasury yields and the Dollar—and those variables determine Gold’s direction.
In 2021, Gold traded around $1,756 immediately before the October NFP and reached roughly $1,782 intraday on October 8, but surrendered much of that move and closed near $1,757, Monday price gap $1685 RT $1717 witnessed. That is a useful example of a large NFP-day move failing to become a durable breakout. StatMuse
In 2022, Gold had already rallied strongly during Golden Week, rising from roughly $1,661 on October 3 to above $1,729 on October 4. But the October 7 employment report was stronger than expected, strengthening expectations for another large Fed hike; spot Gold fell about 0.6% that day. It subsequently traded down toward the mid-$1,660s by October 10. StatMuse
In 2023, September payrolls shocked at +336,000 versus +170,000 expected. Treasury yields and DXY rose and Gold initially fell, trading around $1,814 during the immediate reaction. This again demonstrated the classic transmission mechanism: strong jobs → higher-for-longer Fed expectations → yields/USD higher → Gold pressure. MarketScreener
In 2024, September payrolls came in at +254,000 versus +140,000 expected, unemployment unexpectedly fell to 4.1%, Treasury yields jumped and the Dollar strengthened. Spot Gold slipped to roughly $2,650. Yet Gold subsequently had a strong October overall; the World Gold Council says USD Gold gained 4.9% for the month, showing why the initial NFP reaction should not automatically be extrapolated across the following weeks. Reuters
In 2025, October was again highly volatile rather than one-directional: Gold reached a record $4,294 on October 20, then surrendered much of the intra-month advance before finishing around $4,012, still approximately 5% higher for October. The World Gold Council attributed the month’s dynamics to volatility, geopolitical risk, momentum reversal, profit-taking and Dollar strength. World Gold Council
My conclusion from these five years: Golden Week itself has not produced a dependable bullish or bearish XAU/USD direction. What it can do is change the market’s liquidity and participation structure around an already powerful US macro catalyst.
My NFP-Day Scenario
The first scenario is a much stronger-than-expected NFP.
If payrolls materially exceed the current ~100K consensus, particularly alongside stronger wages or lower unemployment, markets could increase the probability of another Fed hike.
Strong NFP → Fed Hike Expectations ↑ → US2Y/US10Y ↑ → DXY ↑ → XAU/USD ↓
With Gold already below its major daily moving averages, this could expose lower support areas. On your framework, $4,085 → $4,040 → $3,990/$3,969 become increasingly important areas to monitor.
The second scenario is a weak NFP.
A significant downside employment surprise, especially if accompanied by higher unemployment or weaker wage growth, could reduce expectations for further tightening.
Weak NFP → Fed Hike Expectations ↓ → Treasury Yields ↓ → DXY ↓ → XAU/USD ↑
Because Gold has already experienced substantial liquidation, that combination could produce a disproportionately sharp retracement.
The immediate technical recovery test would be the $4,290–$4,330 SMA cluster. A move into this region alone would still be a retracement. A sustained daily recovery above it would begin to weaken the bearish structure.
The Most Dangerous Scenario: Whipsaw
For me, this deserves particular attention.
Gold is already technically stretched, Chinese markets will be closed, and NFP directly affects the market’s Fed expectations.
We could therefore see:
Initial NFP Spike ↓ → Liquidity Sweep → Yields/DXY Reverse → Gold Rebounds
or:
Initial NFP Spike ↑ → Resistance Rejection → Yields/DXY Recover → Gold Falls
This is why I would not judge Friday’s direction from the first NFP candle alone.
What Could Happen the Following Week
China does not return until October 8. Shanghai Gold Exchange
That creates two distinct phases.
October 1–7: XAU/USD trades without normal Shanghai Gold Exchange participation. NFP, US yields, DXY, Oil and geopolitical headlines could therefore dominate international price discovery.
From October 8: Chinese markets reopen. This is where I would watch whether Shanghai prices validate or reject the international Gold move that occurred during the holiday.
The World Gold Council notes that Golden Week traditionally begins China’s peak Gold-buying season, with jewellery sales, trade restocking and local premiums historically becoming important. But 2026 demand has been softer because of elevated prices and weak consumer confidence. World Gold Council
Therefore, I would not automatically assume that Chinese reopening means Gold will rise.
My YAI Projection Framework
From the current ~$4,135 area, I see three logical paths rather than one fixed forecast.
Bearish continuation: Strong NFP + yields remain elevated + DXY strengthens → $4,085 → $4,040 → $3,990/$3,969 becomes the downside map.
Relief retracement: Weak NFP + Treasury yields retreat + DXY weakens → Gold could attempt a recovery toward $4,290–$4,330.
Major reversal: Gold would need more than an NFP bounce. I would want to see yields and DXY materially reverse, Gold reclaim $4,290–$4,330, and eventually challenge the $4,519–$4,539 structural resistance region.
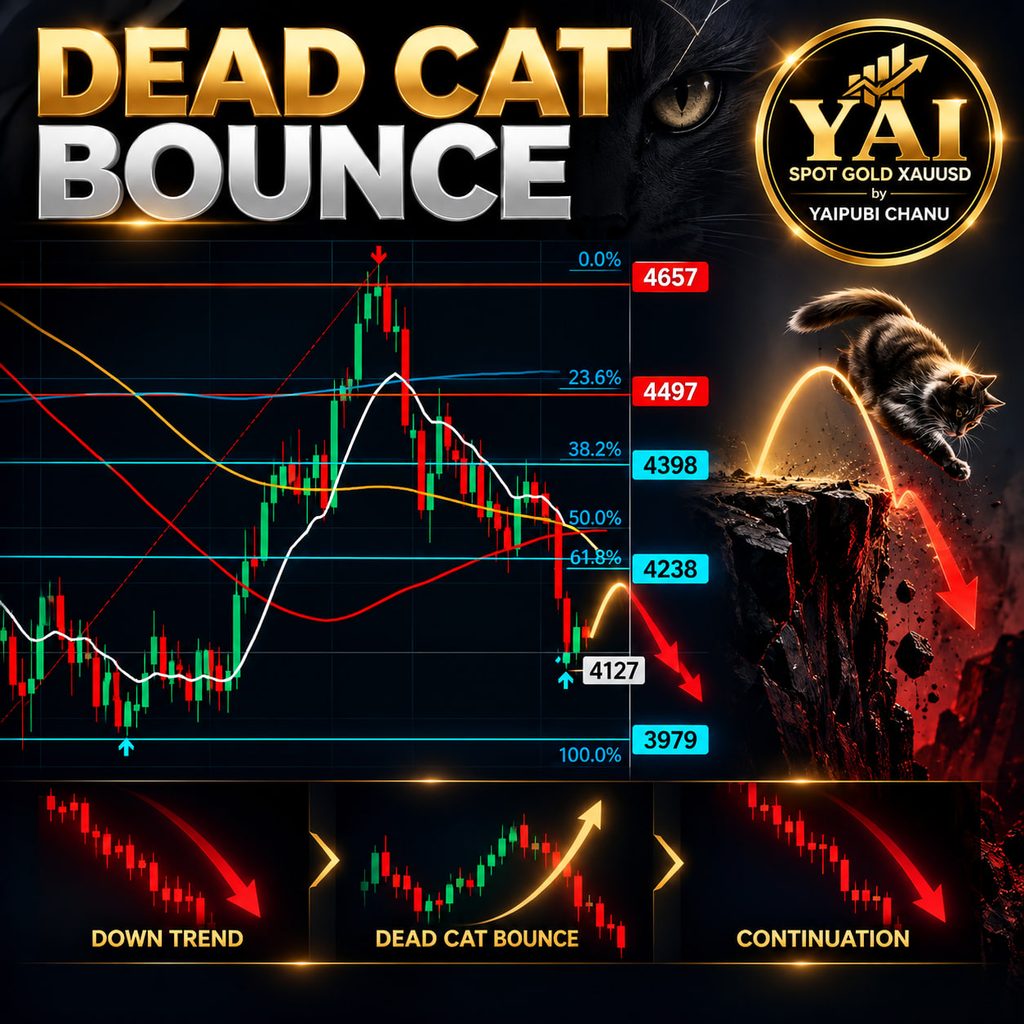
Until those conditions appear, a rally from current levels could still be a technical retracement or dead-cat bounce rather than confirmation of a new bullish trend.
My Key Focus
For this NFP, I will watch the sequence rather than simply the headline number:
NFP → FED EXPECTATIONS → US2Y/US10Y → DXY → XAU/USD
And because China is closed:
THINNER CHINESE PARTICIPATION + NFP SURPRISE = POTENTIALLY LARGER SHORT-TERM PRICE DISLOCATION
The last five years tell me something important: NFP can produce the first move, but yields, the Dollar, positioning, geopolitics and post-Golden-Week Chinese participation determine whether that move survives.
— Yaipubi Chanu | YAI